NEW ZEALAND police tell of a 19-year-old girl who went directly to a seller and offered to buy an Auckland property… for cash.
The seller thought that was a tad unlikely and called her agent, who checked and declared it legitimate.
Even better, the young lady wanted to buy five properties, cash on the barrelhead.
The agent seemed satisfied; police were not. Just one example, they believe, of the estimated NZ$1.35 billion in dirty money laundered (or attempted) in New Zealand each year.
It’s a racket being stamped on by the NZ AML/CFT Act, which has applied to lawyers and conveyancers since 1 July 2018.
The NZ Department of Internal Affairs, which supervises AML for casinos, lawyers, conveyancers, accountants, realtors and betting agencies, tells the AC the sector has adapted well.
“Audits, inspections, and other engagements by DIA indicate good overall compliance,” a spokesperson said.
That may be so, but some practitioners say compliance can have a high price.
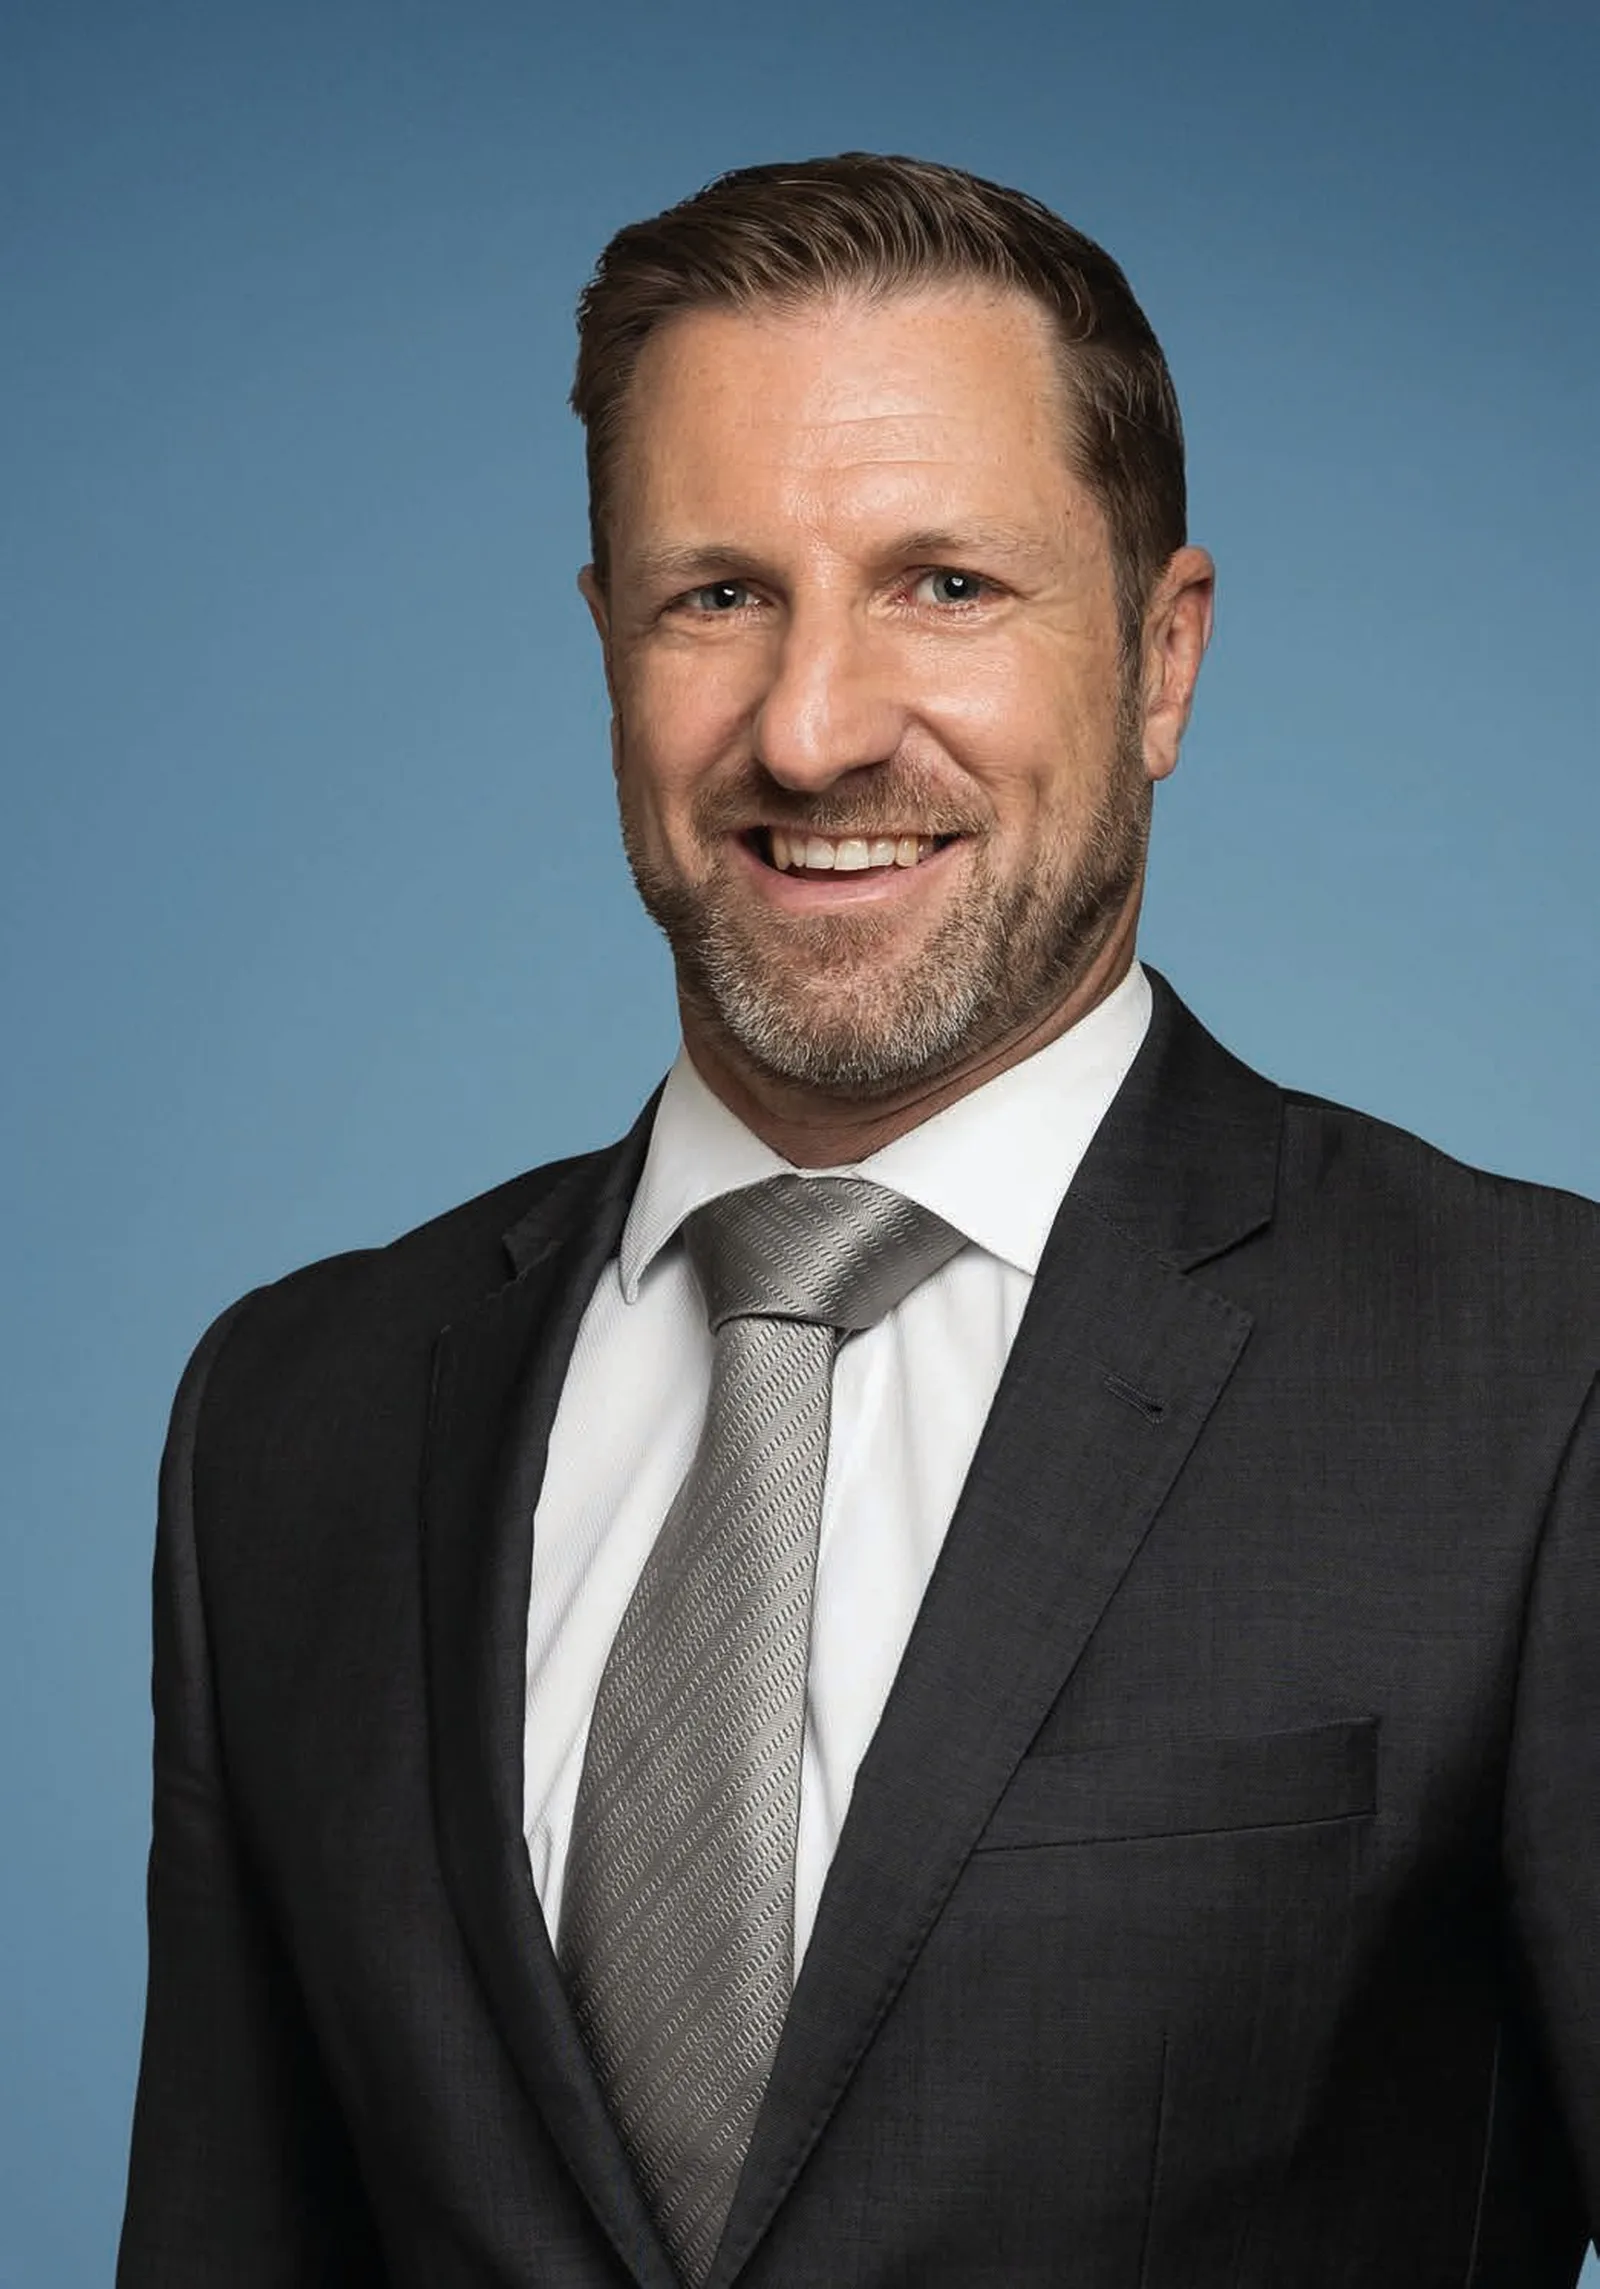
“We spent a fortune,” says lawyer Shaun McGivern, who heads the property division at Auckland’s Haigh Lyon Lawyers.
Their initial AML program which began in 2017 included vetting and training for some 45 staff and cost around $17,000, using outside consultants.
However, when factoring their own directors’ time the actual cost would have equated to nearly $30,000.
“We didn’t really know what was involved, given AML at this level was in its infancy, but we wanted to get things right,” says McGivern. “And for that reason, we felt we needed external advice.”
Now the firm employs a full-time compliance manager – at some cost – while staff and clients have become used to the regime.
“It is what it is, the cost is the cost, you can’t avoid it,” says McGivern.
Some long-established customers, though, chafe at being subject to due diligence. “They say, ‘You’ve been our lawyers for 30 years, handled umpteen property transactions’. But it has to be done.”
Another criticism was an apparent duplication of effort, with the same money sources being checked by financial advisers, banks, realtors and lawyers.
“They (the government) say it’s because there can be laundering done at any stage,” McGivern adds, “and each reporting entity may have only a partial or different view of the same client or transaction.”
There have been successes: such as the Russian seeking to transfer cash from Papua New Guinea for a multi-million-dollar Auckland property.
He turned out to be a PEP or a Politically Exposed Person. The approach was reported, and the Russian disappeared. But the firm’s investigation cost it $8,000.
“We’ll never recover that money,” says McGivern. “But if we’d made a mistake, we’d be the ones in front of the authorities.”
Penalties can be severe: this June an Auckland foreign exchange was fined NZ$1.125 million for failing to report more than $19 million in dodgy transactions.
New Zealand’s DIA now oversees some 6,000 reporting entities. It issues codes of practice for each industry, and there is regular face-to-face education.
Typical classes include free, two-hour “goAML” sessions conducted by the NZ Police Financial Intelligence Unit.
In a YouTube interview, Detective Superintendent Greg Williams of the NZ Police National Organised Crime Group says the aim is to make “know your customer” a natural part of business.
“Who are they?” he asks. “Where are they from? How did they come by their money? Who do they represent?”
Compliance will seem frustrating for some, but there’s a reason for it, he says.
“It’s about protecting our reputation, our way of life, protecting our people,” Williams says.
McGivern agrees: “We have to be seen as a safe place to transact, so you have to go through with it.”